Chip Stocks Fell 11%. Our S&P 500 Panel Flagged an Epicenter for One Day.
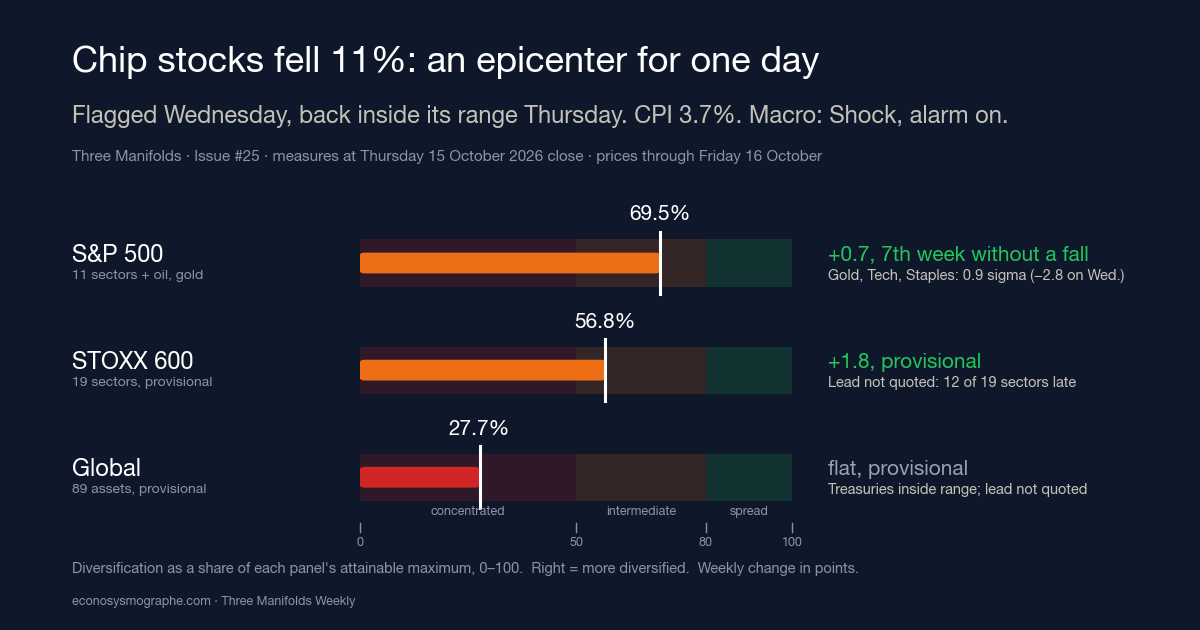
Consumer prices rose 3.7% in the year to September, the Bureau of Labor Statistics reported on Wednesday 14 October, and the S&P 500 fell 1.1% that day. One direction of our panel of eleven S&P 500 sectors, oil and gold moved far enough from its own history on Wednesday to be flagged as an epicenter, and was back inside its range on Thursday, when the panel’s diversification stood at 69.5%, a seventh week without a decline. Chip stocks lost 11% between Fridays and the KOSPI 16% between Thursdays. Friday’s S&P 500 close of 7,659.44, down 1.1%, came after our reading.
Manifold data as of Thursday 15 October 2026 close · Market data through Friday 16 October · 11 min read
The reading in 30 seconds
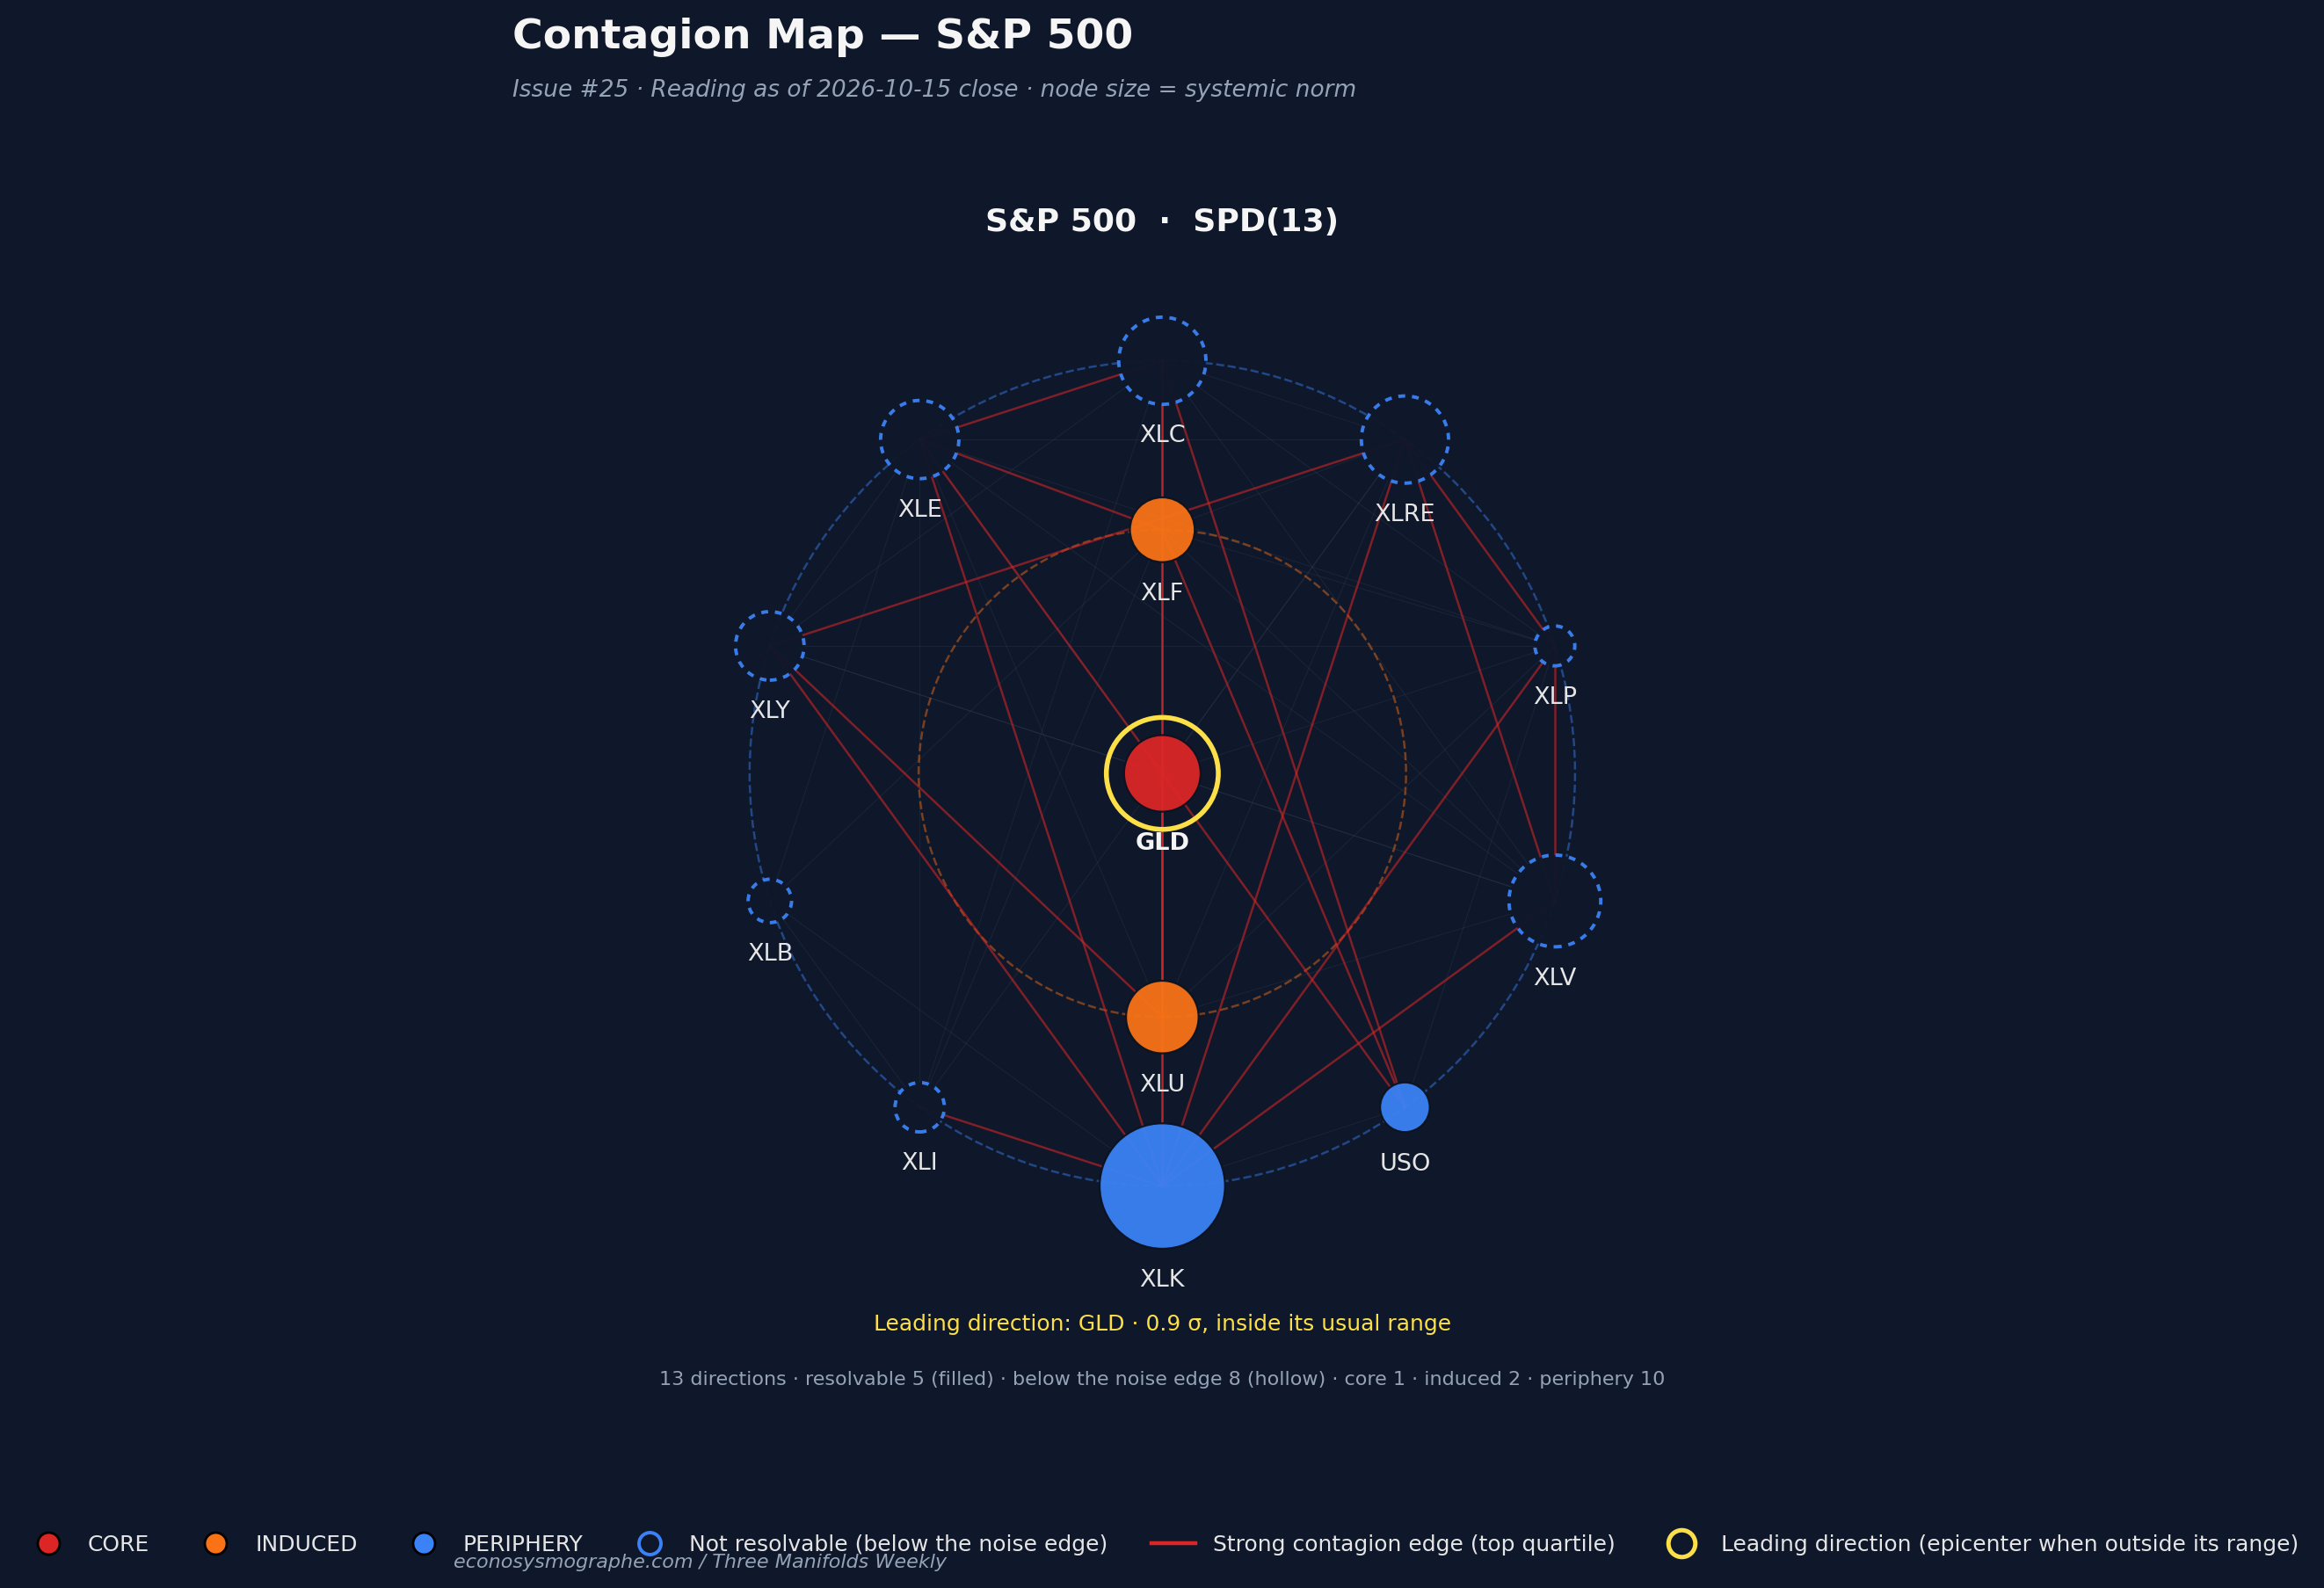
Our panel of eleven S&P 500 sectors, oil and gold rose from 68.8% to 69.5% of its attainable diversification between Thursdays, after 70.0% on Tuesday, its highest since 12 March. On Wednesday a direction tying gold to Technology and Consumer Staples read minus 2.76 standard deviations from its history, outside its range, and the model flagged it as an epicenter. On Thursday it read 0.91, inside its range.
In the composite of 89 assets, on runs in which fifteen series arrived late, the direction that groups Treasuries stayed inside its range on every session while the ten-year yield fell 12 basis points. The macro state has read Shock for twenty-one sessions, and the shock alarm, off for five sessions, switched on again on Thursday.
See this reading on your own book →
The week
Prices came first. On Wednesday 14 October the Bureau of Labor Statistics reported that the consumer price index rose 0.6% in September and 3.7% over twelve months. The index excluding food and energy rose 2.6% on the year. On Thursday the Bureau reported that the producer price index for final demand rose 1.3% in September and 6.3% over twelve months. The S&P 500 closed Wednesday at 7,718.94, down 1.1% on the day, and Thursday at 7,744.06, down 0.3% from the 7,765.36 of the previous Thursday. Its highest close of 2026 remains the 7,818.93 of 6 October.
Chip stocks fell further. The Philadelphia semiconductor index closed Friday 16 October at 11,137.29, down 11.4% from 12,572.42 a week earlier, the last of those sessions after our reading, and the Nasdaq Composite lost 4.5% over the same five sessions. The KOSPI closed Thursday at 5,554.22, down 7.6% on the day and 16.2% from the 6,625.93 of the previous Thursday, with the Seoul exchange closed on Friday 9 October. On Thursday MSCI opened a consultation on reclassifying its Indonesia indexes from emerging-market to standalone status, and on Friday the Jakarta Composite fell 11.6% to 5,185.10.
Treasury yields fell. On the Treasury’s daily par curve the ten-year closed at 5.19% on Wednesday and 5.10% on Thursday, down 9 basis points in one session and 12 on the week, its lowest close since the 4.96% of 22 September, while the two-year rose from 4.75% to 4.77% and the gap between the two narrowed from 47 to 33 basis points. The ICE BofA MOVE index of Treasury volatility closed at 102.49 on Thursday, from 100.70. The VIX closed at 16.46 on Thursday and, after our reading, at 19.99 on Friday, its highest close since 29 July.
The Brent spot price on the Energy Information Administration’s daily series eased from $130.18 on Thursday 8 October to $126.55 on Wednesday 14 October, the last value published before our reading, and the agency’s release of 15 October left unchanged the $135.51 of 2 October that Issue #24 reported. In Europe, Eurostat confirmed on Friday that euro-area inflation reached 3.8% in September, from 3.2% in August, and the STOXX Europe 600 rose 2.1% between Fridays, its largest Friday-to-Friday gain since the 2.7% of the week to 3 July.
New York: an epicenter on Wednesday, none on Thursday
The panel’s diversification score measures how evenly its correlation structure is distributed across directions of co-movement, for thirteen assets, eleven S&P 500 sectors with oil and gold, and stood on Thursday at 69.5% of the ceiling a panel of that size can attain, from 68.8% a week earlier and 61.5% on 27 August. It read 70.0% on Tuesday, its highest since the 70.1% of 12 March, and 69.8% on Wednesday.
That Wednesday the lead of the panel, a direction tying gold to Technology and Consumer Staples, read minus 2.76 standard deviations relative to its own history, outside its range. The model flagged it as an epicenter, the first in this panel since 28 September. On that day the same direction had read outside its range at 3.03, also for a single session. On Thursday it read 0.91, inside its range, and still led. Of the panel’s thirteen directions, the model could resolve five on Thursday, above the noise edge defined in the annex. The four others read 0.86 for the oil fund with Financials and Industrials, 0.81 for gold with Utilities and Technology, 0.79 for Industrials with Materials and Financials, and minus 0.29 for the oil fund with Energy and Staples, the last two classified as absorbing stress rather than transmitting it. The gold direction was the only core direction that day. Financials, which Issue #24 had found alone in the periphery for a fourth week, now enter the induced direction with the oil fund and Industrials and the absorbing one with Industrials and Materials.
Europe: provisional, up, and the lead not quoted
The European panel’s provisional diversification score was 56.8% on Thursday, against 55.0% a week earlier, up 1.8 points. Both figures are read in the following day’s run, the convention we apply to a panel whose runs are not reproducible from one day to the next: Thursday’s own run had read 57.9%. Twelve of the nineteen sector series were carried forward in each of the week’s runs, for a third week, so the lead is not quoted. The last lead we could quote for this panel was on Thursday 24 September, a direction tying Media, Basic Resources and Health Care, at 0.81, inside its range.
Under the panels: the alarm switched on again on Thursday, the state still Shock
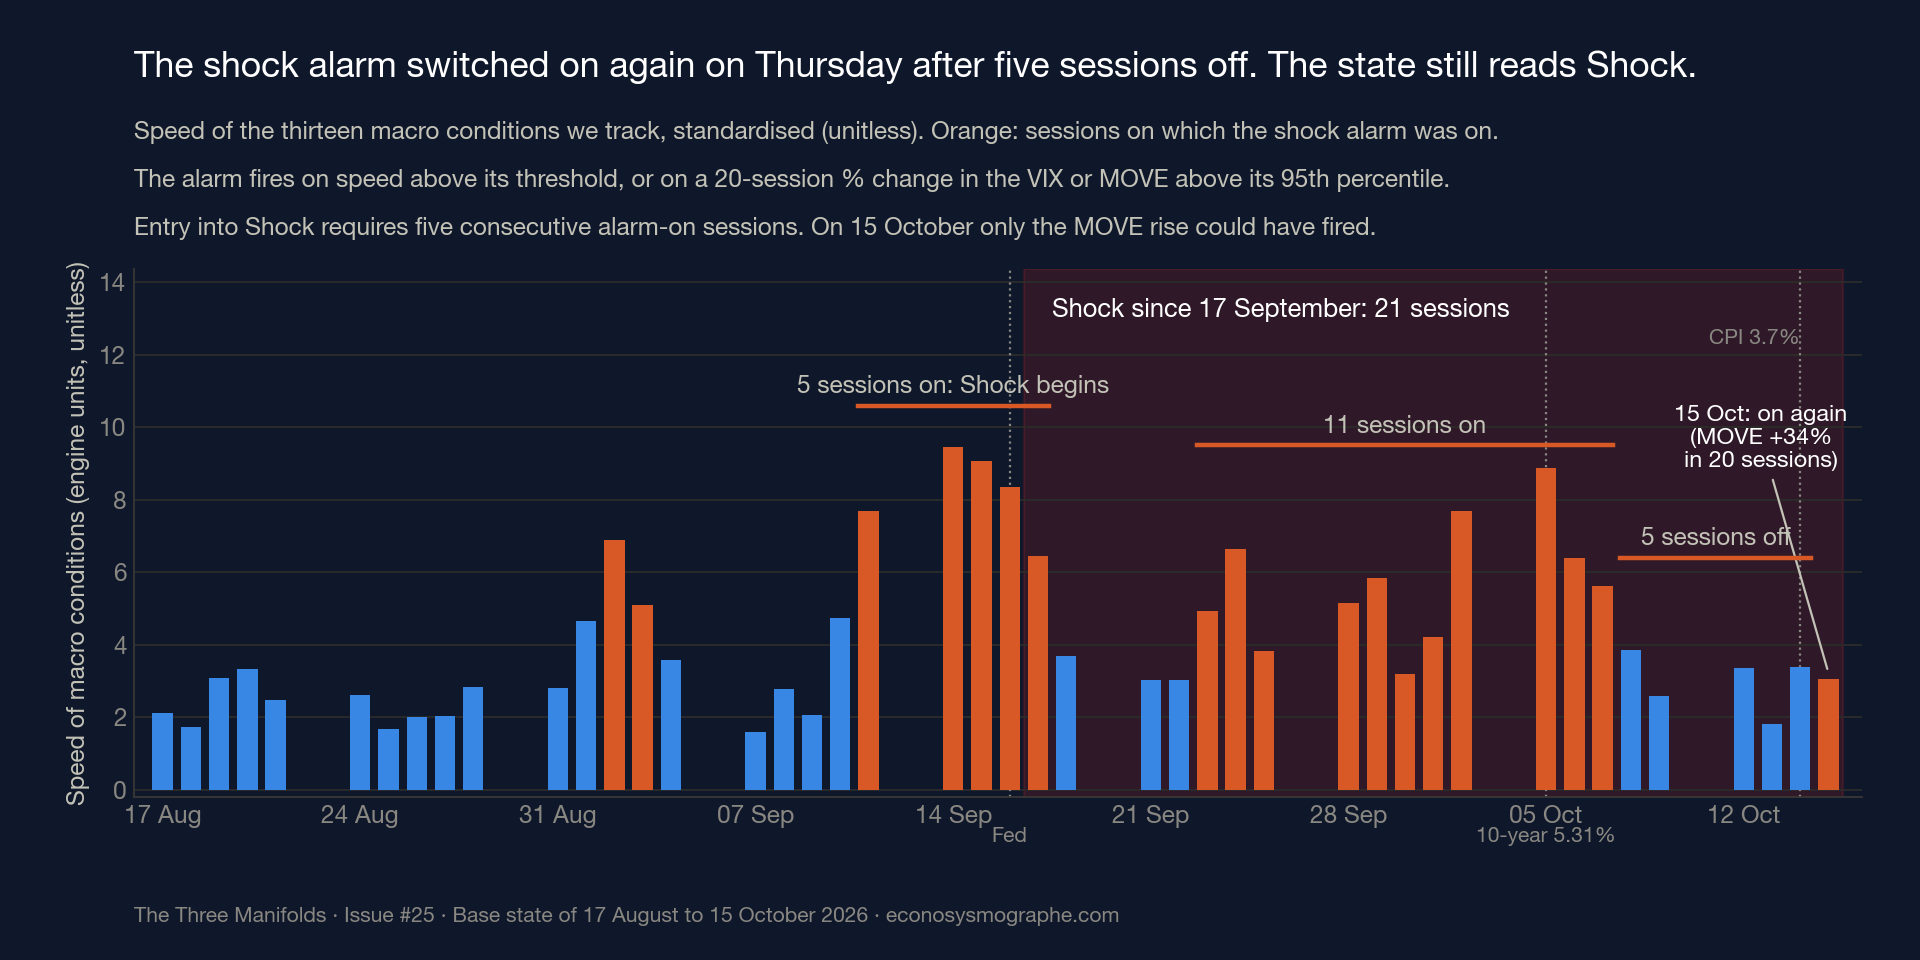
The fast layer of our macro state, which sorts thirteen conditions such as real yields, the two yield curves, volatility and the dollar into named regimes, has read Shock since Thursday 17 September, twenty-one sessions through Thursday, longer than two of the five completed Shock episodes since December 2023, which ran 16, 20, 36, 51 and 31 sessions. The shock alarm, through which the state is entered, had switched off on Thursday 8 October after eleven sessions on, stayed off on the five sessions from 8 to 14 October without the state changing, and switched on again on Thursday 15 October.
The alarm fires on any of three conditions: the speed of the thirteen conditions above its threshold, fixed at calibration, or the twenty-session percentage change in the VIX or in the MOVE index above its own 95th percentile. On Thursday the MOVE index stood 34% above its level of twenty sessions earlier, 102.49 against 76.22 on 17 September, a rise of 26.27 points and a twenty-session percentage change of 34%. The speed read 3.06, and the VIX stood 7% above its level of twenty sessions earlier. Both sit below readings on which the alarm had stayed off earlier in 2026, a speed of 4.94 on 20 April and a VIX rise of 43% on 20 January, and the thresholds are fixed, so the MOVE condition is the one that fired. The business cycle, on the OECD’s leading indicator, read Expansion on every session of the week.
The composite of 89 assets, which reads the two sector panels together with rates, currencies, commodities and the other regions, read 27.7% of its ceiling on Thursday against 27.6% a week earlier, flat and provisional, at 27.5% in Friday’s run. Fifteen of its 89 series reached each of the week’s runs late, among them the three Treasury yields, which these runs carry forward by one session. On those runs the direction that groups Treasuries read between minus 0.13 and 1.20 from 9 to 15 October, inside its range throughout, and the direction that groups oil read minus 1.50 at the furthest, on Wednesday. Both are readings of the runs available, not of a composite refreshed with Thursday’s closes. The composite’s lead was a different direction on each session, a rotation we cannot separate from the late series, so we quote none.
Technology: the Korean memory makers left their range, the CoreWeave direction did not
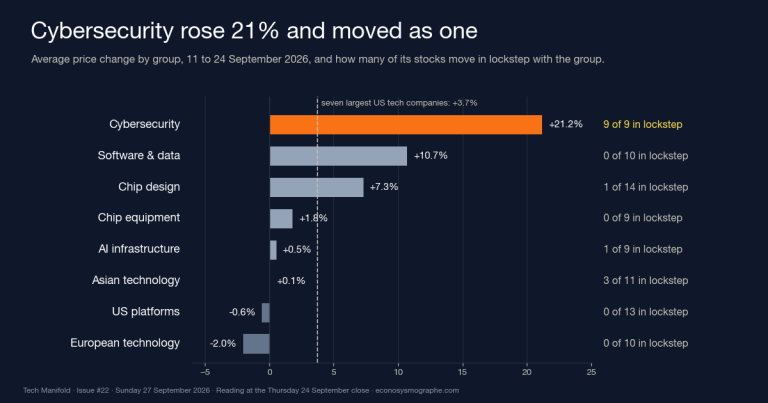
Group returns are equal-weighted averages of constituent stock returns between two closes. Between the closes of 8 and 15 October the nine AI-infrastructure stocks in our Tech panel returned an average of −11.3%, the nine chip-equipment makers −10.5% and the fourteen chip designers −6.2%, while the thirteen US platforms returned +1.7% and the ten European stocks +1.6%. SK Hynix fell 24.9% and Samsung Electronics 19.9% between the closes of 8 and 15 October, four Seoul sessions. On Thursday alone they fell 11.1% and 9.5%.
A direction tying those two memory makers to Tencent read minus 1.67 on Tuesday 13 October, outside its range and the lead of the panel that day, and minus 1.91 on Thursday, outside its range again. The direction that led the panel on 1 October, tying CoreWeave, Synopsys and SK Hynix, read between minus 1.39 and 0.52 on the week’s five sessions, inside its range on each, including Wednesday, when CoreWeave fell 15.5%. The direction tying Ericsson, Nokia and Cisco read 1.31 at the highest, on Thursday, the day Ericsson published its third-quarter report and rose 11.8%. The panel’s level, around 52% of its ceiling and up on the week, is provisional, with six of its series late in Thursday’s run. These directional readings are provisional too, because they are estimated from the full panel. The direction ranked first changed on every session, so we quote none as the lead.
The audit: last week’s five checks, and the results
Last Sunday we wrote down five things this issue would report, whichever way they went. Three are complete, one rests on provisional runs, and one could only be read in part. The direction checks use absolute standardised readings, the convention by which a direction is found outside its usual range.
Macro state, complete. We had asked whether the fast layer had left Shock on any session from 9 to 15 October, and it had not, a twenty-first session on Thursday. The alarm, off from 8 to 14 October, switched on again on Thursday.
New York diversification, complete. We had asked whether the panel read below 66.0% on any session from 9 to 15 October, and it read 69.7%, 69.7%, 70.0%, 69.8% and 69.5%.
New York directions, complete. We had asked whether any resolvable direction, transmitting or absorbing, read at least 1.64 in absolute value on Thursday 15 October, and the most unusual read 0.91. The check was written for Thursday. The epicenter of Wednesday, at minus 2.76, falls outside that window.
Treasuries, provisional. We had asked whether the direction that groups Treasuries in the composite read at least 1.64 in absolute value on any session from 9 to 15 October, in runs that receive the Treasury closes a day late, and it read 1.20 at the furthest, on Thursday, on runs in which the three Treasury yields were among fifteen late series.
Technology, read in part. We had asked whether the direction tying Ericsson, Nokia and Cisco read outside its range on any session from 9 to 15 October, and it read 1.31 at the highest. We had also asked whether all nine cybersecurity stocks still read in lockstep on Thursday. The count that answers that question was not produced by Thursday’s run. The last count, for Tuesday 13 October, read nine of nine, a twenty-second session, and the average correlation among the nine over thirty sessions read 0.77 on Thursday against 0.74 a week earlier.
For an allocator
What follows is diagnostic and not prescriptive. This week’s reading points to three things to examine in a book, with the book’s own holdings and weights, which our panels do not contain.
The first is how much of the book’s technology exposure sits in the two Korean memory makers and in the stocks that moved with them. The direction tying them to Tencent read outside its range on Tuesday and Thursday, and the direction that led the panel two weeks ago did not.
The second is whether the book’s own diversification moved with the sector panel’s. The panel’s score cannot establish whether a particular portfolio became more or less diversified through the week. That requires a separate calculation on its holdings and weights, the one we run on a book.
The third is which holdings are sensitive to changes in Treasury-market volatility, the condition that switched the shock alarm on again. It fired on the twenty-session rise in Treasury volatility, not on the speed of the thirteen conditions, while the macro state remained in Shock. The positions to examine first are those whose value moves with long-term rates and with the volatility of those rates: Treasuries, and the duration carried in credit and in rate-sensitive equities.
Before Issue #26
Issue #26 reads Thursday 22 October. Five checks for next week are set down here before the fact, and the issue will report each result.
- Macro state: whether the fast layer has left Shock on any session from 16 to 22 October and, if so, for which state, and whether the alarm, on again on 15 October, was on or off on Thursday 22 October. Thursday 15 October: Shock, alarm on.
- New York diversification, threshold 66% of the attainable: whether the panel read below 66.0 on any session from 16 to 22 October, and whether it read 70.0 or above on any of them. Thursday 15 October: 69.5, and Tuesday 13 October: 70.0.
- New York directions, threshold 1.64 standard deviations: whether any resolvable direction, transmitting or absorbing, read at least 1.64 in absolute value on any session from 16 to 22 October. The window is the week, because this week’s epicenter fell on a Wednesday. Wednesday 14 October: minus 2.76, and Thursday 15 October: 0.91 at most.
- Treasuries: whether the direction that groups Treasuries in the composite of 89 assets read at least 1.64 in absolute value on any session from 16 to 22 October, in runs that receive the Treasury closes a day late. Thursday 15 October: 1.20.
- Technology: whether the direction tying SK Hynix, Samsung Electronics and Tencent, outside its range on 13 and 15 October, still read at least 1.64 in absolute value on Thursday 22 October, whether the direction tying CoreWeave, Synopsys and SK Hynix read outside its range on any session from 16 to 22 October, and, if Thursday’s run produces the count again, whether all nine cybersecurity stocks still read in lockstep on 22 October. Thursday 15 October: minus 1.91, and 0.52. Last count of the lockstep, Tuesday 13 October: nine of nine.
The Energy Information Administration publishes its next Brent spot values on Wednesday 21 October. The Federal Open Market Committee meets on 27 and 28 October, and the European Central Bank’s Governing Council on 28 and 29 October. Eurostat publishes its flash estimate for October on 4 November, and the Bureau of Labor Statistics the October consumer price index on 10 November.
- The platform → econosysmographe.com/platform · Methodology → econosysmographe.com/methodology · Glossary → econosysmographe.com/glossary · contact@econosysmographe.eu
Notation annex → The measures are experimental research metrics from the Universal Risk Framework (SSRN working papers), not market standards. The diversification score is the TSS: how evenly the panel’s correlation structure is distributed across directions of co-movement (100% = evenly spread; low = concentrated); its zones are Singularity, Tension and Isotropic, on the dimension-normalised TSS* with thresholds at 50 and 80; all diversification percentages quoted in this article are TSS*, the score as a share of the ceiling a panel of that size can reach. A panel of n assets has n directions of co-movement; a direction is resolvable when its weight stands above the noise edge of the panel’s spectrum, and only resolvable directions are read. The leading direction is, among the resolvable directions the model classifies as transmitting stress to the others, the one whose reading is the most unusual relative to its own history, in standard deviations; it is named an epicenter only when it reads outside its usual range, that is when the absolute value of its standardised reading is at least 1.64, signed readings keeping their sign; core / induced / periphery rank every direction of the panel, resolvable or not. Lockstep: a stock’s curvature reading measures how tightly it is bound to the other stocks of its group through the group’s correlation structure; a stock is in lockstep when that reading exceeds the 90th percentile of its own past. The reading has no sign and says nothing about the direction of prices. The macro state has two layers: a slow one, the business-cycle phase read from the OECD composite leading indicator, and a fast one that sorts thirteen macro conditions into named regimes and overrides the slow one when conditions move quickly; the Shock state is entered after five consecutive sessions on which the shock alarm is on, and the alarm is on when the speed of those conditions exceeds its threshold, whatever their direction, or when the twenty-session percentage change in the VIX or in the MOVE index exceeds its own 95th percentile. Readings are taken on the last settled session, Thursday; Friday’s session is read in Tuesday’s brief. Full methodology at econosysmographe.com/methodology.
Sources. Bureau of Labor Statistics, Consumer Price Index, September 2026, released 14 October 2026, and Producer Price Index, September 2026, released 15 October 2026 (index levels on FRED CPIAUCNS, CPIAUCSL, CPILFESL, PPIFIS). U.S. Energy Information Administration, Europe Brent Spot Price FOB, daily, 8 to 14 October 2026, release of 15 October 2026 (FRED DCOILBRENTEU). U.S. Treasury, Daily Treasury Par Yield Curve Rates, 8 to 16 October 2026, and the 2026 file. FRED: SP500, NASDAQCOM, DGS10, DGS2, DGS30, VIXCLS, BAMLC0A0CM (ICE BofA US corporate OAS), closes of 8 to 16 October 2026. ICE BofA MOVE index closes. Cboe: VIX closes. Exchange closing values of the PHLX Semiconductor index, the KOSPI (Korea Exchange), the Jakarta Composite and the STOXX Europe 600, 8 to 16 October 2026, and the STOXX Europe 600 Friday closes since May 2026, read on a public market-data feed. MSCI, announcement of 15 October 2026 on a consultation to reclassify the MSCI Indonesia Indexes from Emerging Market to Standalone Market status. Eurostat, euro area annual inflation, September 2026, released 16 October 2026. Ericsson, third-quarter report 2026, 15 October 2026. Federal Reserve, FOMC meeting calendar for 2026; European Central Bank, Governing Council calendar for 2026; Bureau of Labor Statistics and Eurostat release calendars. Exchange closing prices (Nasdaq, NYSE, Nasdaq Stockholm, Nasdaq Helsinki, Korea Exchange, Hong Kong) of the stocks of the Tech panel, 8 to 15 October 2026. OECD, Composite Leading Indicator. Econosysmographe: Global Systemic Composite SPD(89), S&P 500 SPD(13), STOXX 600 sector panel, Tech Manifold panel and its group hierarchy, Base V3. Manifold data as of Thursday 15 October 2026 close. Raw payloads on request.
Disclaimer & Regulatory Status. This document is published for sophisticated, professional, and institutional readers for informational and educational purposes only. It does not constitute investment research within the meaning of regulatory frameworks, nor is it an offer, solicitation, or recommendation to buy or sell any financial instrument. SmartGreenInvest Ltd (Reg. England & Wales No. 14636473) is not an FCA-regulated firm. All analyses are based on public quantitative data and geometric modeling as of the date of publication. Opinions expressed are subject to change without notice. Historical performance and model readings are not indicative of future results. SmartGreenInvest Ltd holds no positions in the issuers named. The author is a self-directed, long-term buy-and-hold investor in US technology equities, at a scale immaterial to the market capitalisations discussed.
By Evangelos Papadopoulos · Independent Researcher · econosysmographe.com